Health Insurance Medical Insurance
Understanding health insurance medical insurance: costs, rates, and benefits explained
Choosing the right health insurance medical insurance plan can be overwhelming, especially with so many providers, coverage options, and pricing tiers. Whether you’re self-employed, employed, or looking for family coverage, it’s crucial to understand how health insurance medical insurance works, what it covers, how much it costs, and the benefits it offers.
What is health insurance medical insurance?

Health insurance medical insurance is a contract between an individual and a provider that helps cover the cost of medical care. This includes routine check-ups, emergency services, hospitalization, prescriptions, and in many cases, specialist care and preventive services.
There are different types of health insurance medical insurance plans available, such as:
- Individual plans: For those without employer-sponsored insurance
- Family plans: Designed to cover multiple people under one policy
- Employer-sponsored plans: Offered through your job
- Public options: Such as Medicare or Medicaid (in the U.S.)
- Short-term coverage: Temporary protection during life transitions
Benefits of health insurance medical insurance
The core benefit of health insurance medical insurance is financial protection. Unexpected medical bills can be catastrophic. With a proper policy, you pay monthly premiums but avoid massive out-of-pocket expenses when illness or injury occurs.
Other major benefits include:
- Access to preventive care: Annual check-ups, screenings, and vaccines
- Prescription coverage: Reducing medication costs
- Specialist visits: Referrals to cardiologists, dermatologists, etc.
- Emergency services: Ambulance and urgent medical care
- Mental health support: Therapy, counseling, and psychiatric treatment
How much does health insurance medical insurance cost?
The cost of health insurance medical insurance varies widely depending on your location, age, health condition, income, and the type of plan you choose.
Here’s a breakdown of typical costs in 2025 (U.S. averages):
- Monthly premiums: Between $400 and $700 for an individual
- Deductibles: Range from $1,500 to $5,000 annually
- Co-pays: $20 to $50 per visit
- Out-of-pocket maximums: Usually $8,000 or more per year
If you're buying a health insurance medical insurance policy through a government marketplace, your income may qualify you for subsidies that reduce your premiums and out-of-pocket costs.
Comparing health insurance medical insurance plans
When shopping for health insurance medical insurance, consider the following factors to find the plan that best suits your needs and budget:
- Monthly premium: What you pay each month regardless of service usage.
- Deductible: What you must pay out-of-pocket before insurance kicks in.
- Network coverage: Are your preferred doctors and hospitals included?
- Prescription coverage: Are your medications on the covered list?
- Out-of-pocket maximum: The most you’ll pay in a year for covered services.
- Co-insurance & co-payments: Your share of the costs after reaching your deductible.
A plan with a lower monthly premium often has higher out-of-pocket costs and vice versa. It’s essential to evaluate your healthcare usage habits when deciding.
Who needs health insurance medical insurance?
Everyone can benefit from having health insurance medical insurance, including:
- Young adults: Even if you’re healthy, accidents or unexpected illness can occur.
- Families: To protect children and other dependents.
- Seniors: Especially important for age-related conditions and medications.
- Self-employed individuals: Without employer coverage, private plans are essential.
- Part-time workers or freelancers: Flexible plans or public options may apply.
Going without health insurance medical insurance can leave you exposed to debt and limited medical care access.
Can you get health insurance medical insurance internationally?

Yes, many health insurance medical insurance providers offer international coverage for travelers, digital nomads, and expatriates. These plans can include emergency evacuation, hospital care abroad, and global telemedicine services.
If you frequently travel or reside in another country, consider a global health insurance medical insurance plan to ensure you're covered regardless of your location.
Are there free or low-cost health insurance medical insurance options?
In some countries, public healthcare or subsidized options make health insurance medical insurance more affordable:
- Medicaid (USA): For low-income individuals and families
- ACA Marketplace subsidies (USA): Based on income
- Public insurance systems: In countries like Canada, the UK, and Germany
Always check what government-sponsored or employer-based options are available to you before committing to a private plan.
Tips for choosing the right health insurance medical insurance
Here are a few final tips to guide your decision:
- Compare at least 3 different health insurance medical insurance plans.
- Read the fine print: Know what is and isn’t covered.
- Consider a health savings account (HSA) if using a high-deductible plan.
- Review customer service ratings and claim processes.
- Don’t just focus on cost—look at value and long-term benefits.
-
Investing in health insurance medical insurance is one of the smartest financial decisions you can make. It not only protects your physical health but also your financial stability. Whether you're young and healthy or managing chronic conditions, having the right health insurance medical insurance gives you peace of mind and access to the care you deserve.
Si quieres ver mas Noticias, Recetas, Eventos, Conocer lugares y todo lo relacionado con Guatemala, únete a nuestros grupos Telegram y Whatsapp.[](/noticias/cultura/comida-tipica-semana-santa-guatemala-prueba-estos-10-deliciosos-platillos/)
Artículos relacionados
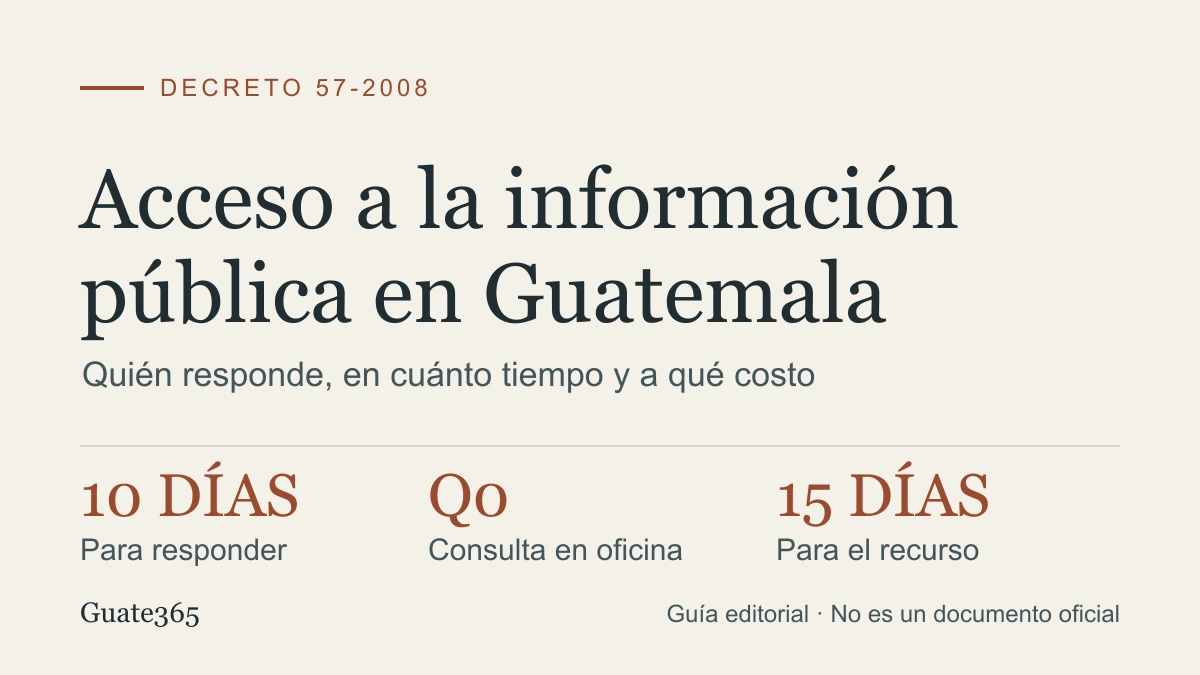
Ley de Acceso a la Información Pública: cómo solicitarla
Qué permite la Ley de Acceso a la Información Pública, cuánto cuesta pedir datos, el plazo de 10 días y el recurso de revisión si te los niegan.
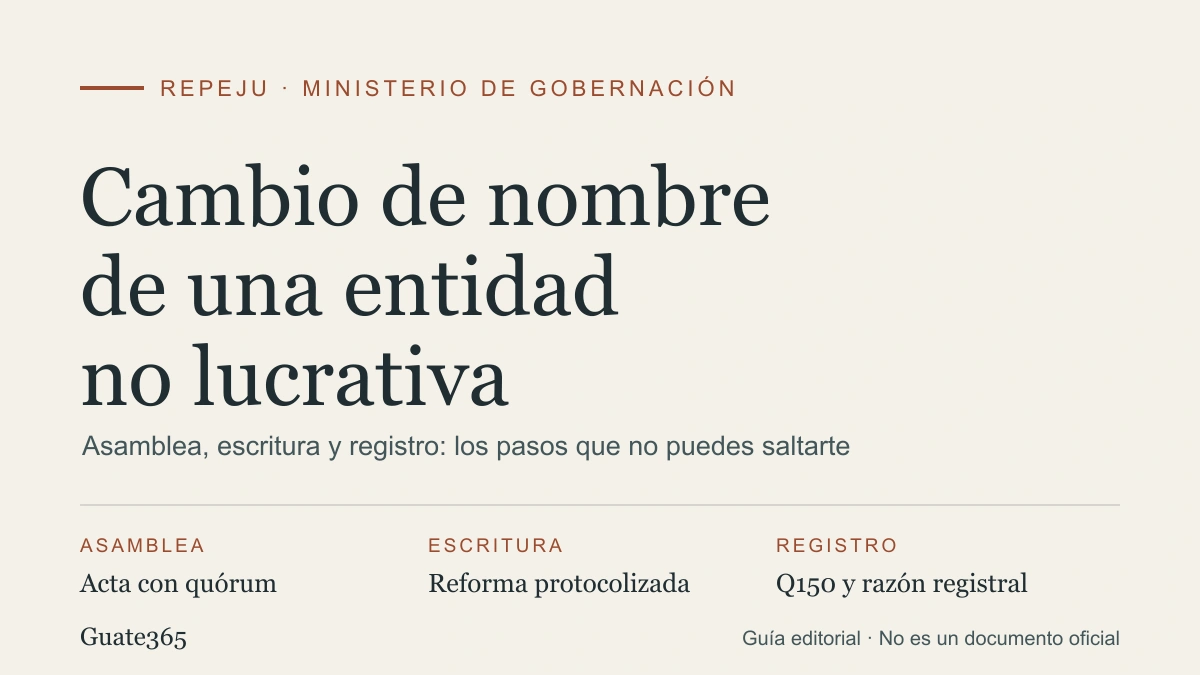
Cambio de nombre de una entidad no lucrativa: REPEJU y SAT
Cómo cambiar el nombre de una asociación, fundación u ONG en el REPEJU: requisitos, arancel de Q150 o Q200 y el aviso a la SAT en 30 días hábiles.
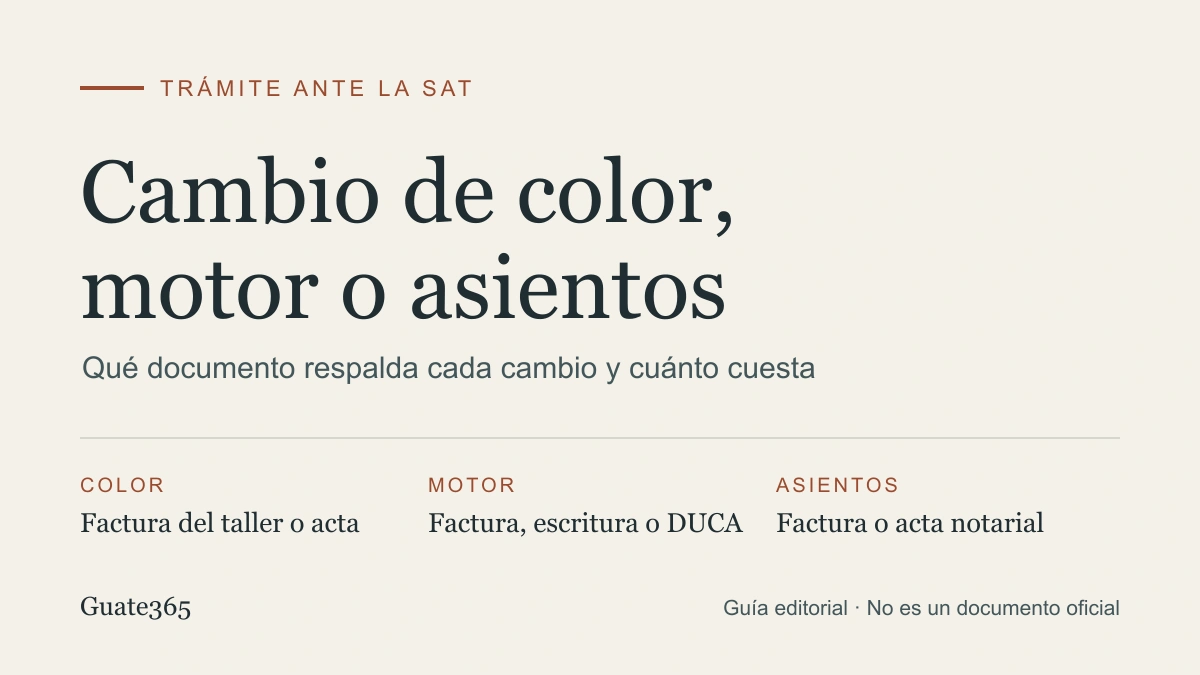
Cambio de color o motor del vehículo: cómo tramitarlo en la SAT
Cómo registrar en la SAT un cambio de color, motor o asientos, qué documento respalda cada caso y cuánto se paga.
Solicitud de NIT en línea: pasos, costo y requisitos del trámite
Cómo pedir el NIT en línea en el Portal SAT: requisitos, costo real, los 10 días hábiles del formulario y cuándo debes terminar el trámite en una agencia.